Hard Assets Outraise Credit as Alts Sales Fall 14% Through September
Alternative investment fundraising totaled $134.4 billion through September 2026, down 14% from $156.4 billion in the same period of 2025, according to the latest analysis from investment banking firm Robert A. Stanger & Co. Credit strategies raised $42.5 billion year-to-date, down 48% year-over-year, while non-credit fundraising increased 24% to $91.9 billion.
HALO strategies – hard assets with low obsolescence, consisting of real estate and infrastructure – raised $44.7 billion through September, a 39% year-over-year increase. These strategies now lead credit by $2.2 billion year-to-date, widening the narrow lead first reported in August. Infrastructure fundraising rose 67% year-over-year to $22.8 billion, while real estate increased 18% to $21.9 billion. Hard assets have now outraised credit in six consecutive months.
Year-to-date 2026 gross fundraising by investment strategy, compared with the same period in 2025, is summarized in the table below.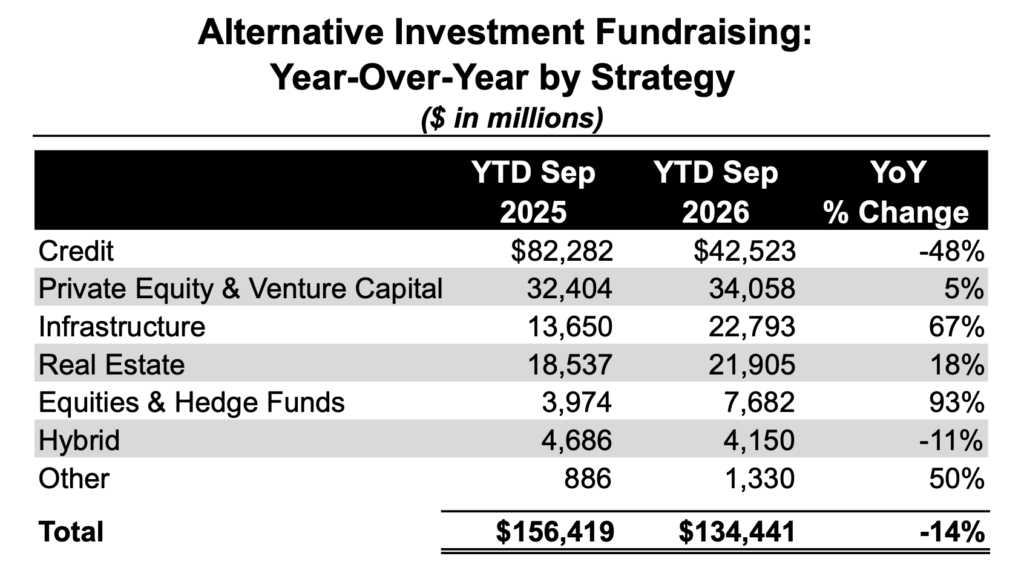 The divergence was particularly pronounced in the third quarter. HALO strategies raised $16.3 billion, up 54% from the third quarter of 2025, while credit fundraising fell 61% to $11.1 billion. The resulting $5.3 billion gap marked the second consecutive quarterly lead for hard assets and a reversal from the third quarter of 2025, when credit raised roughly 2.7 times as much as real estate and infrastructure combined.
“The overall decline in fundraising doesn’t tell the full story,” said Kevin T. Gannon, chairman and chief executive officer of Stanger. “Credit is weighing heavily on the totals, but outside of credit, capital formation is growing at a healthy pace. The market isn’t slowing down across the board – it’s slowing in credit, while real estate and infrastructure keep gaining ground.”
Business development companies remain the largest contributor to the credit pullback. Combined publicly registered and private placement BDC fundraising totaled $18.8 billion through September, down 62% from $49.1 billion in the same period of 2025. Publicly registered nontraded BDCs raised $8.6 billion year-to-date, down 76%, while private placement BDCs raised $10.2 billion, down 27%.
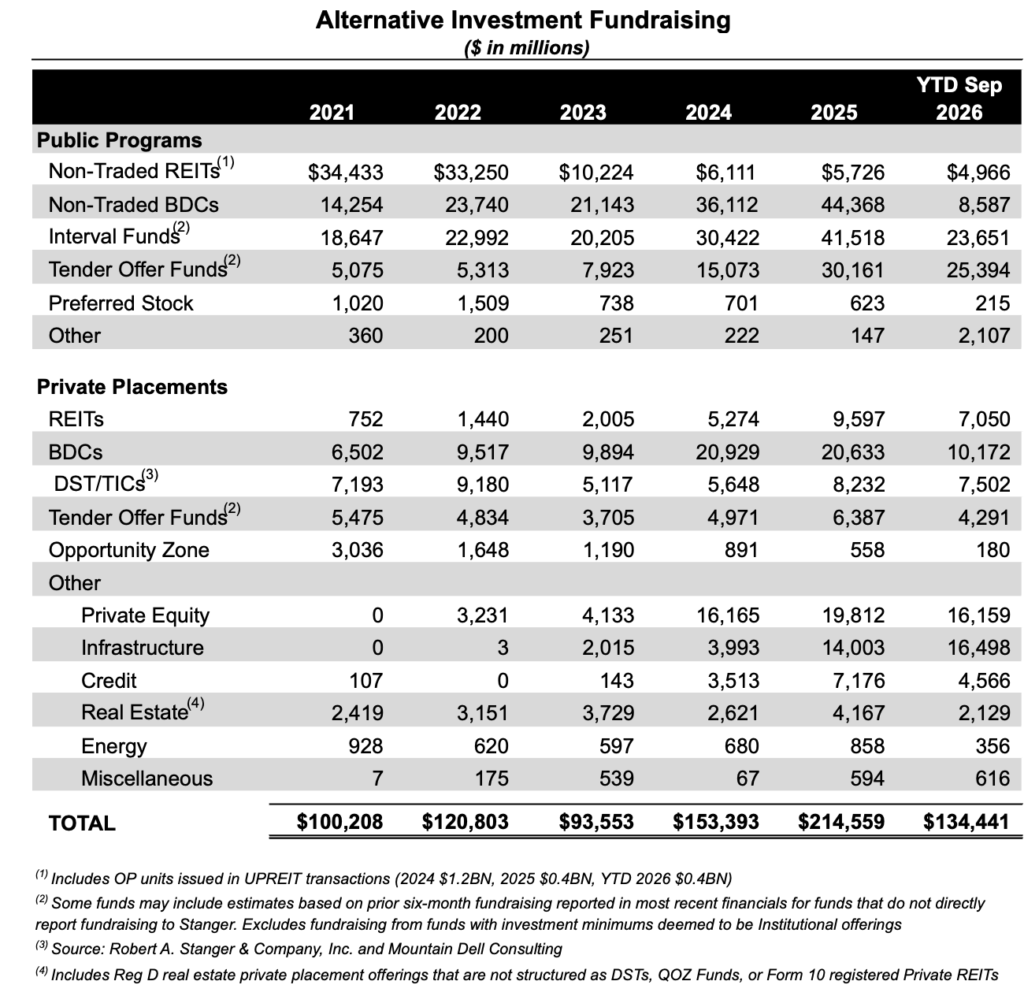
Private placement vehicles raised $69.5 billion through September, up 10% year-over-year, while public programs raised $64.9 billion, down 30%. Private placements accounted for 52% of year-to-date fundraising, up from 40% a year earlier. In the third quarter, private placements accounted for more than 55% of fundraising, their second consecutive quarter ahead of public programs.
Cliffwater’s Cascade Real Assets Fund, a new real estate-focused interval fund that became effective in August, raised $895 million in its first closing in September, expanding Cliffwater’s interval fund platform into hard assets alongside its existing credit and private equity strategies.
Year-to-date gross fundraising by product category through September 2026, compared with prior full-year totals, is summarized in the table below.
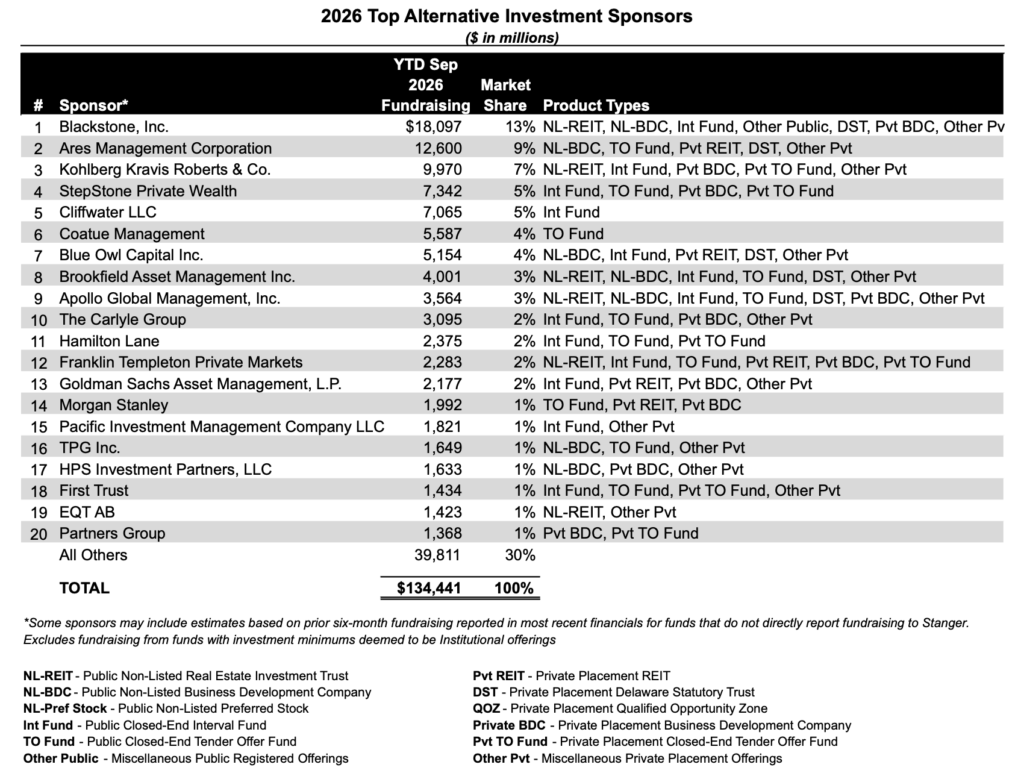
 The top 20 sponsors by year-to-date gross fundraising are shown below. The top five are Blackstone (13% market share), Ares Management Corp. (9%), KKR & Co. (7%), StepStone Private Wealth (5%), and Cliffwater (5%).
 Founded in 1978, Robert A. Stanger & Co. Inc. is an investment banking firm providing advisory, valuation, and capital markets services to real estate investment trusts, partnerships, and related entities.
Visit the AltsWire directory page.