Alts Fundraising Hits $119B Through August as Hard Assets Pass Credit
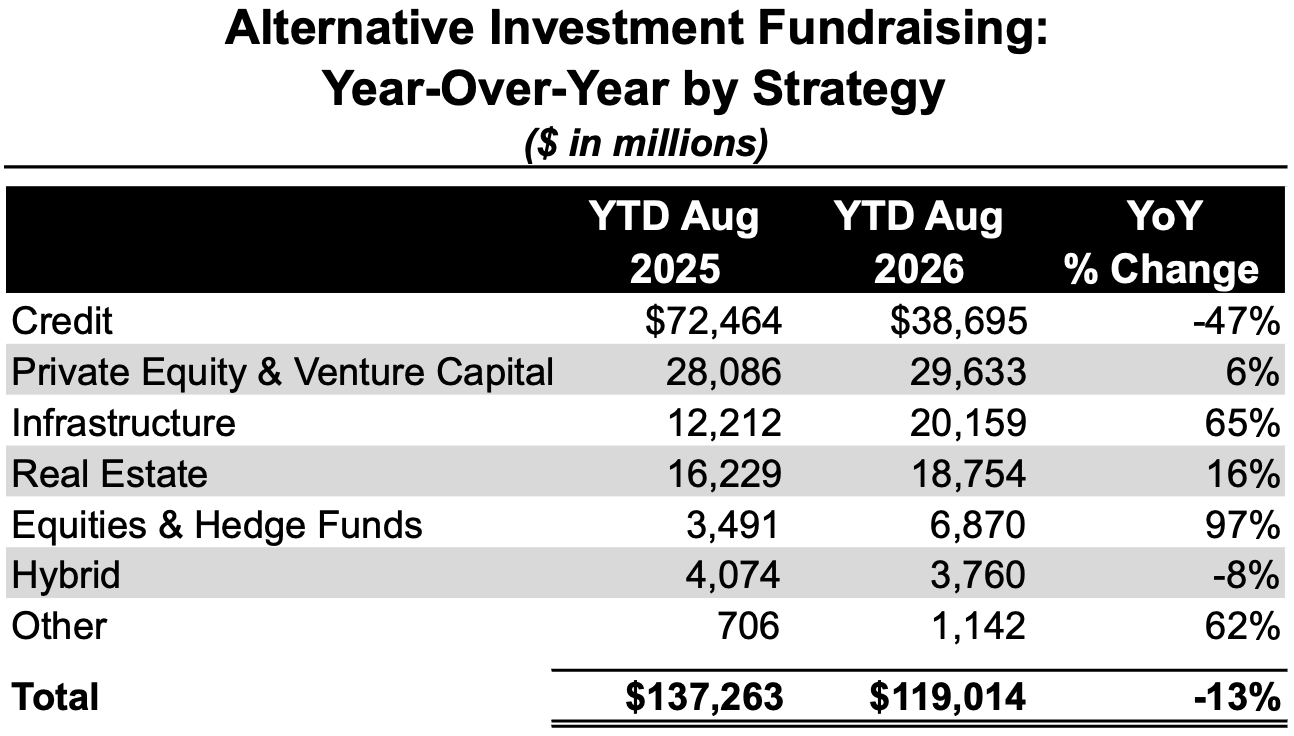
Alternative investment fundraising totaled $119 billion through August 2026, up 14.1% from the previous month but down 13% from $137.3 billion in the same period of 2025, according to investment bank Robert A. Stanger & Co. The decline remained concentrated in credit strategies, where year-to-date fundraising fell 47% to $38.7 billion from $72.5 billion a year ago. Excluding credit, fundraising increased 24% year over year to $80.3 billion.
HALO strategies – hard assets with low obsolescence, consisting of real estate and infrastructure – raised $38.9 billion through August, up 37% from $28.4 billion in the same period last year. Infrastructure remained the primary driver of growth, raising $20.2 billion, up 65% year over year, while real estate strategies raised $18.8 billion, up 16%. At $38.9 billion, year-to-date HALO fundraising has now edged ahead of the $38.7 billion raised by credit strategies, with hard assets outraising credit in each of the past five months.
Year-to-date 2026 gross fundraising by investment strategy, compared with the same period in 2025, is summarized in the table below.
“Hard assets moving ahead of credit is a meaningful marker in a rotation we have been tracking all year,” said Kevin T. Gannon, chairman and chief executive officer of Stanger. “The crossover is narrow, but the shift behind it is not. A year ago, credit had raised more than two-and-a-half times as much as real estate and infrastructure combined through August. Investors are not leaving alternatives; they are reallocating, and the monthly data has pointed in the same direction since April.”
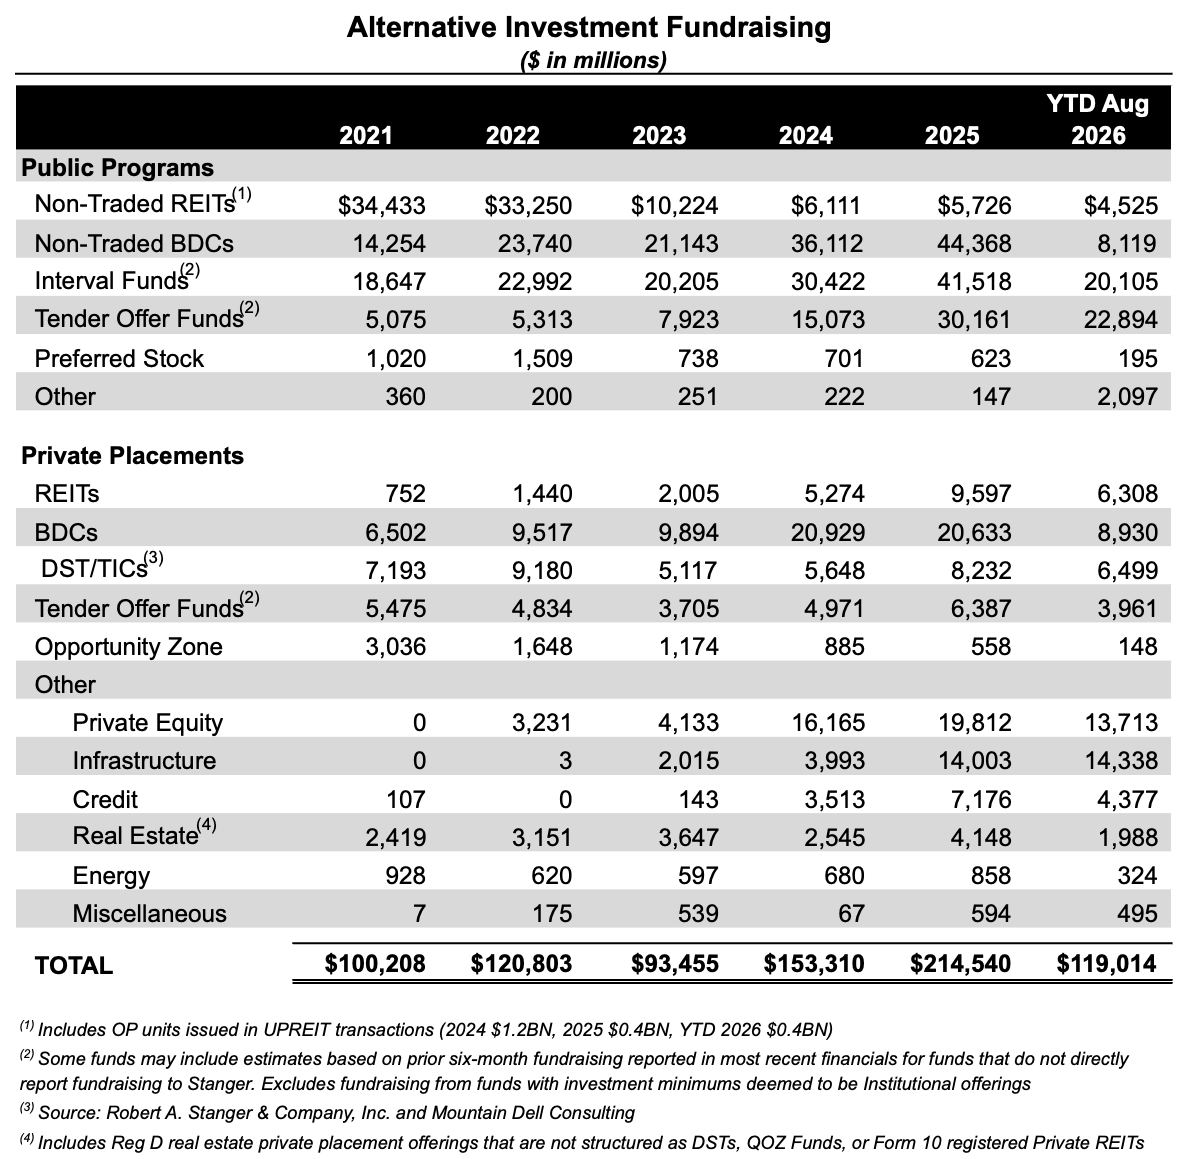
Fundraising by business development companies remains the single largest source of the credit decline. Combined publicly registered and private placement BDC fundraising totaled $17 billion through August, down 60% from $43 billion in the same period of 2025. Publicly registered nontraded BDCs raised $8.1 billion, down 74%, while private placement BDCs raised $8.9 billion, down 22%. Private placement BDCs have now moved ahead of their publicly registered counterparts on a year-to-date basis, a reversal from the same period last year, when publicly registered BDCs raised nearly three times as much.
The shift toward private offerings extends beyond BDCs. Private placement vehicles raised $61.1 billion through August 2026, up 12% from $54.6 billion in the same period of 2025. Public programs raised $57.9 billion, down 30% from $82.6 billion. Private placements accounted for 51% of total year-to-date fundraising, up from 40% a year earlier.
“Investors are changing how they access alternatives as much as what they are buying,” Gannon said. “Private placements represented roughly a quarter of year-to-date fundraising five years ago; today, they account for more than half. That is a structural change in how alternative investment capital is being raised.”
Year-to-date gross fundraising by product category through August 2026, compared with prior full-year totals, is summarized below.
The top 20 sponsors by year-to-date gross fundraising are shown below. The top five are Blackstone (14% market share), Ares Management Corp. (9%), KKR & Co. (7%), StepStone Private Wealth (6%), and Cliffwater (5%).
As recently reported by AltsWire, Blackstone Real Estate fully subscribed its first Delaware statutory trust offering, a $175.6 million deal under its Blackstone Real Estate Exchange program, or BXREX. The DST holds two Class A multifamily properties in the Sunbelt with more than 600 units.
Founded in 1978, Robert A. Stanger & Co. Inc. is an investment banking firm providing advisory, valuation, and capital markets services to real estate investment trusts, partnerships, and related entities.
Visit the AltsWire directory page.