After Years of Open-Road Growth, Non-Listed BDCs Enter Hairpin Turn

After several years of full-throttle fundraising, expanding net asset values, and double-digit total return expectations, the non-listed business development company market is now navigating a sharp change in direction, per data and analysis from Robert A. Stanger & Company Inc., an investment banking firm and that specializes in alternative investment industry research.
Aggregate NAV rose 2.9% in the fourth quarter of 2025 to $131.8 billion, a notable downshift from the 9% quarter-over-quarter growth recorded in Q3 2025.
The Stanger NL BDC Index gained 1.8% in Q4 2025, tying its lowest quarterly performance in nearly three years and falling below its 2.6% trailing 10-quarter average, signaling slowing total return momentum.
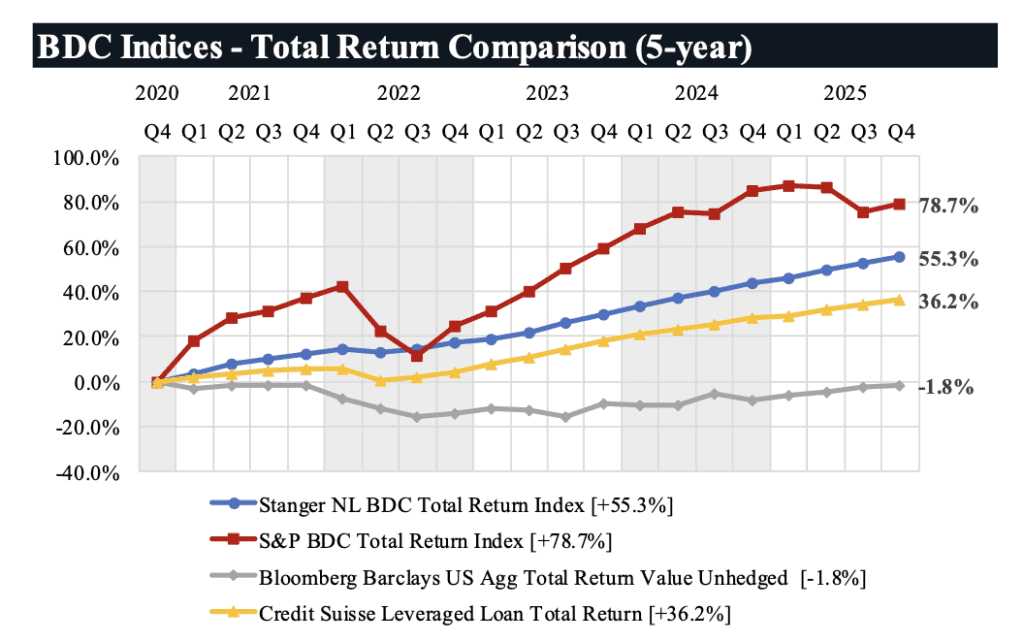 Publicly registered and private placement BDCs surpassed $63 billion of cumulative fundraising in 2025, up 13.9% year-over-year, while publicly registered BDCs alone accounted for $43 billion and saw a 22.6% year-over year increase. Yet recent fundraising data points to additional signs of deceleration, suggesting that while full-year totals remain strong, forward momentum is slowing.
- Cumulative fundraising for publicly registered and private placement BDCs declined 10.1% in Q4 2025;
- BDC cumulative fundraising in December totaled $4.8 billion, down 22.6% from the March 2025 peak of $6.2 billion; and
- December sales for publicly registered BDCs alone fell to $2.3 billion, down 49.8% from the April peak of $4.6 billion.
“The warning lights have been flickering for some time,” said Michael S. Covello, executive managing director at Stanger. “We first saw isolated fraud cases, then distribution rates began trending lower, followed by compression in total returns. Most recently in private credit, investor sensitivity around AI-related exposure and software-heavy portfolios has added another layer of caution. Individually, these were manageable signals. Collectively, they suggest the market was entering a turn.”
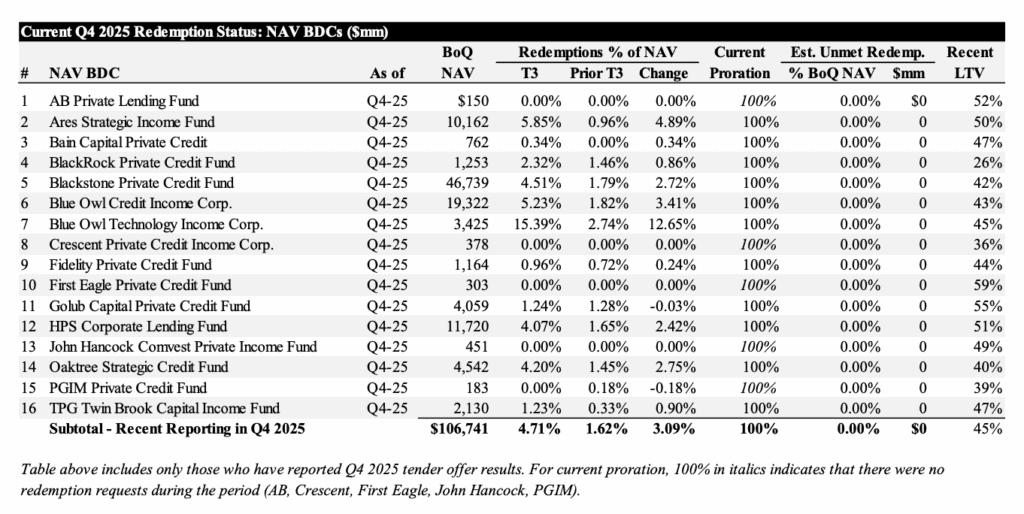
Redemptions accelerated sharply in Q4 2025, with investors becoming more selective as total return expectations compress and liquidity management becomes paramount. As of early February 2026 reporting:
- Redemption rates as a percentage of beginning-of-quarter NAV rose to 4.71% in Q4 2025 from 1.62% in Q3 2025;
- Multiple BDCs exceeded their 5% quarterly cap to satisfy 100% of requests;
- Blue Owl Technology Income Corp. increased its tender cap from 5% to 19%, ultimately repurchasing approximately 15.4% of NAV; and
- Among BDCs with aggregate NAV exceeding $1 billion, redemptions increased 217% quarter-over-quarter.
“The prolonged period of open-road growth for non-listed BDCs is giving way to a hairpin turn,” said Kevin T. Gannon, chairman and chief executive officer of Stanger. “While 2025 marked another record year for capital formation, Q4 data shows slowing inflows, moderating total returns, and rising redemption levels. Importantly, sponsors largely met elevated redemption requests – and in several cases exceeded the standard 5% quarterly cap – demonstrating the structural integrity of the products. As investors reassess risk, capital is beginning to rotate toward tangible, income-durable sectors such as defensive real estate, [triple net lease] structures, and mortgage [real estate investment trusts].”
Gannon added, “Turns don’t end cycles – they reset them. The coming quarters will reveal which platforms are best positioned to navigate tightening liquidity and shifting investor sentiment.”
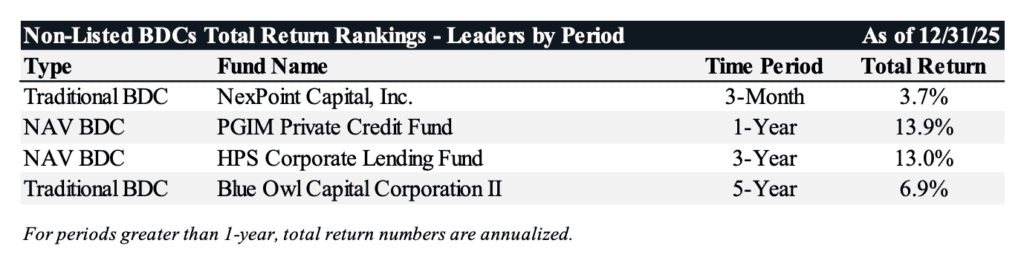
Performance leaders across key time periods are summarized in the table below.
See what AltsWire has reported about the BDC total-return leaders.
- Last month, NexPoint Capital Inc. announced a formal realignment of its board of directors following the recent passing of Bryan A. Ward, a Class I director.
- In summer 2025, Stanger reported PGIM Private Credit Fund topped one-year returns for the third consecutive quarter with a total return of 13.7% while Blue Owl Capital Corp. II once again led the five-year rankings, more than doubling its next closest competitor.
- BlackRock-owned HPS Corporate Lending Fund announced an aggregate NAV of over $12.62 billion as of Nov. 30, 2025, more than a 4% increase from the previous month’s approximate $12.12 billion.
- In December 2025, Blue Owl Capital Corporation II updated its dividend reinvestment plan price to $8.31, a 0.48% dip from the previous month’s $8.35.
Founded in 1978, Robert A. Stanger & Company is an investment banking firm specializing in providing investment banking, financial advisory, fairness opinion and asset and securities valuation services to partnerships, real estate investment trusts, and real estate advisory and management companies in support of strategic planning and execution, capital formation and financings, mergers, acquisitions, reorganizations, and consolidations.
Click here to visit the AltsWire directory page.