Private Placement REITs Raise $4.8B in First Half as BDC Fundraising Drops 18.5%
Private placement real estate investment trusts’ and business development companies’ aggregate net asset value reached a combined $119.3 billion as of June 30, 2026, up 5.6% quarter-over-quarter and 39.0% year-over-year, according to investment banking firm Robert A. Stanger & Co. Inc.
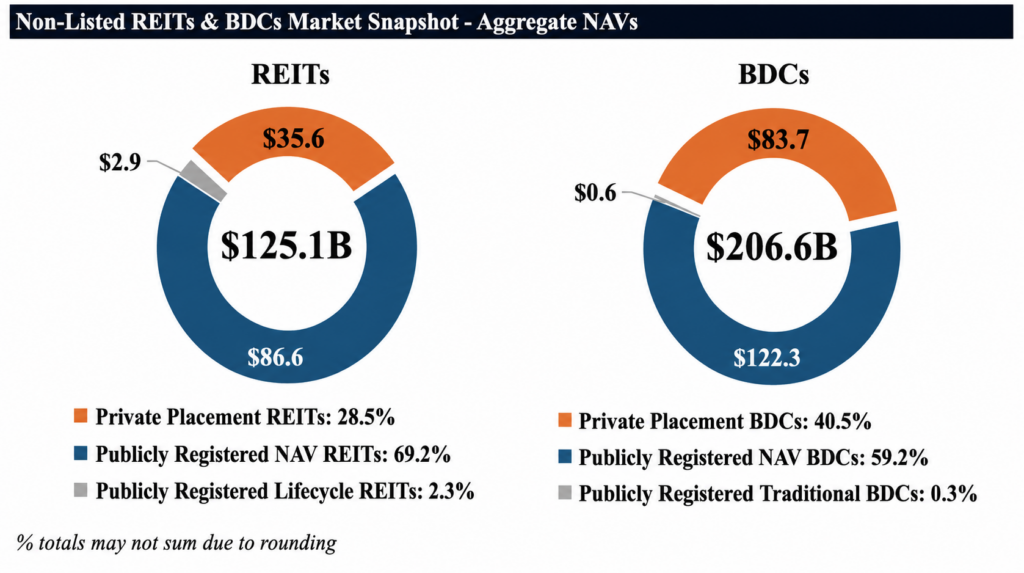
Private placement REITs accounted for 28.5% of the $125.1 billion nontraded REIT market, while private placement BDCs represented 40.5% of the $206.6 billion nontraded BDC market.
Private placement REITs raised $4.8 billion during the first six months of 2026, up 11.8% from the $4.3 billion raised over the same period in 2025 and nearly 41% more than their publicly registered counterparts. Second quarter fundraising totaled $2.5 billion, a 15.1% year-over-year increase.
The pace extends a trend AltsWire has tracked through the year: private placement REIT NAV reached $33.1 billion in the first quarter, up 52.2% year-over-year at the time and representing 26.9% of the nontraded REIT market – a share that has since grown to 28.5%.
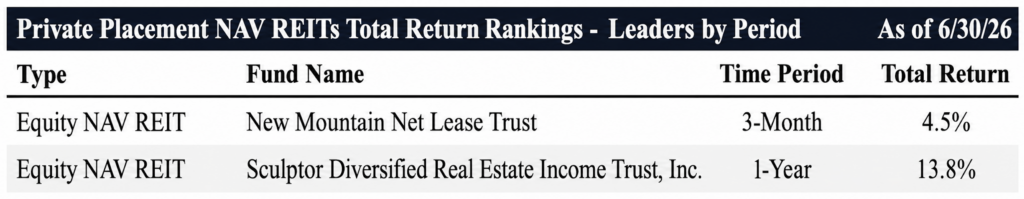
The Stanger Private NAV REIT Total Return Index gained 2.3% in Q2 2026 and 10.1% over the trailing 12 months, according to Stanger, while the Stanger Composite NAV REIT Total Return Index, which incorporates both publicly registered and private placement NAV REITs, gained 2.4% and 8.1%, respectively. All 18 private placement NAV REITs included in Stanger’s quarterly returns summary posted positive second-quarter returns, ranging from 1.1% to 4.5%.
“Capital continues to rotate toward hard assets with low obsolescence, and private placement REITs continue to benefit from that shift,” said Kevin T. Gannon, chairman and chief executive officer of Stanger. “These vehicles have now outraised their publicly registered counterparts for seven consecutive quarters, highlighting their growing adoption across the market.”
Private placement BDC fundraising moved in the opposite direction amid heightened redemption pressure. These vehicles raised $6.9 billion through June 2026, down 18.5% from the $8.5 billion raised during the first half of 2025. Second quarter fundraising totaled $2.8 billion, a 34.3% decline from Q2 2025 and the lowest quarterly total since Q2 2023.
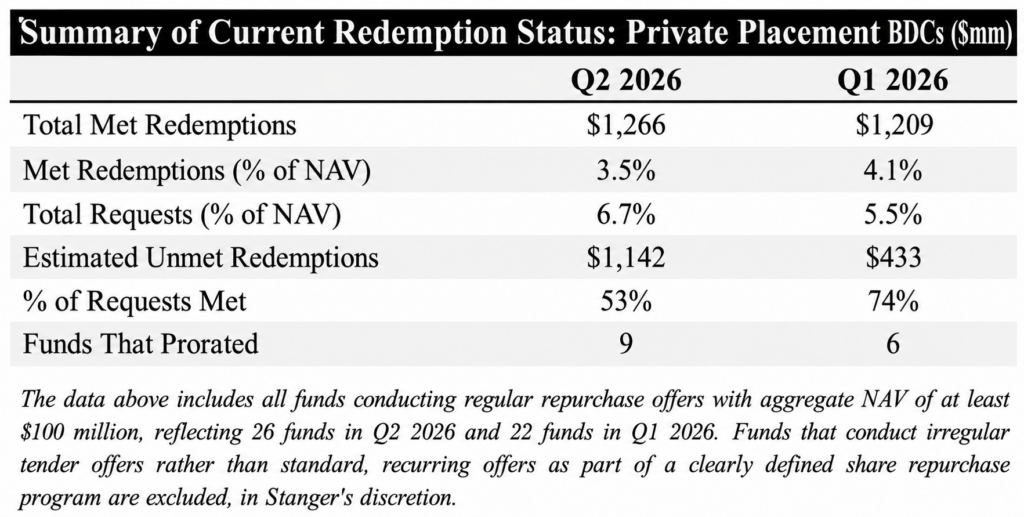
Redemption pressure remained elevated across private placement BDCs. Among the 26 funds conducting regular repurchase offers with aggregate NAV of at least $100 million, Q2 2026 redemption requests equaled 6.7% of NAV. Sponsors met 53% of those requests and returned $1.3 billion to investors, with nine funds prorating and an estimated $1.1 billion left unmet. Across all private placement BDCs, including those that have since reported third-quarter activity, these vehicles have returned $2.6 billion to investors in 2026.
The proration rate marks a step up from earlier in the year: in the first quarter, 19 private placement BDCs that had reported results fulfilled 74% of redemption requests, with five funds prorating, according to Stanger, compared with 53% fulfilled and nine funds prorating in the second quarter.
Early third-quarter reporting shows lower redemption demand, though the sample remains limited. Seven private placement BDCs have reported to date, with repurchase requests equal to 4.5% of NAV versus 7.8% for those same funds in the second quarter. Four funds met 100% of requests and two received no requests. The remaining fund, with approximately $146 million in NAV, met 7% of requests.
“The private placement BDC market is following the same broad pattern we reported in the publicly registered market this quarter, though the magnitude is different,” Gannon added. “Fundraising has contracted, redemption demand is elevated, and proration is doing exactly what it was built to do — balancing liquidity for investors who want out against protection for those who remain. Early Q3 redemption data offers an encouraging initial read, but it remains too limited to call a turn in the liquidity cycle.”
Private placement NAV REIT performance leaders across key time periods are summarized in the table below.
Founded in 1978, Robert A. Stanger & Co. Inc. is an investment banking firm providing advisory, valuation, and capital markets services to real estate investment trusts, partnerships, and related entities.
Visit the AltsWire directory page.